On November 19, Oliver Wyman said it had agreed to acquire Synpulse, a technology consultancy serving banks, insurers and wealth managers. The Marsh business expects the transaction to close in early 2027, subject to regulatory approvals and customary closing conditions. The companies have already staffed projects together. Ownership would let them plan and sell that work as a single business, a material change when the customer is hiring people to work on systems that need to keep running throughout a migration. Oliver Wyman’s announcement · Synpulse’s announcement
The deal terms are undisclosed. The buyer describes approximately 1,200 Synpulse employees working from more than 20 locations and says they will continue to operate across North America, Europe and Asia after closing. That gives the acquisition a visible operating scale even with its financial terms private. The greatest apparent opportunity is to carry more projects from deciding what to change through building it, proving it works and training the people who will keep it running. The value depends on how many specialists stay and how clearly the combined firm assigns responsibility to them.
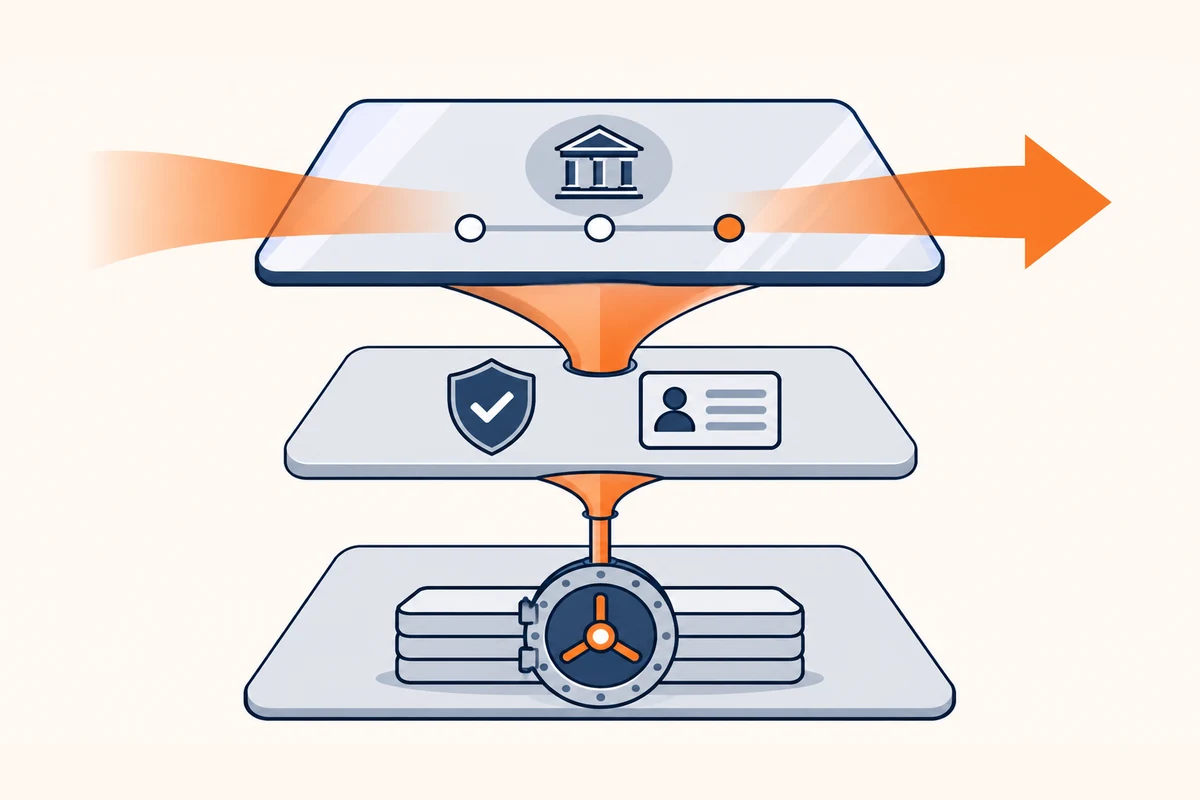
A bank that wants to shorten how long it takes to open an account may discover that part of the delay comes from its digital forms, part from identity checks and part from how information enters its core banking system. A plan that treats all three as a new front end can make the screen prettier while leaving the work underneath as slow as before. Engineers and operations staff who have to carry a change into production can help expose that problem early. That is the commercial promise behind bringing the consultancies together. The account-opening example is illustrative and describes no specific customer.
A larger team carries a larger delivery obligation#
Synpulse dates to 1996. The announcement describes work with financial institutions across technology, design and operations, and identifies Synpulse8 as its technology division. Its network includes more than 100 ecosystem partners. That network matters because large financial institutions already depend on software and services from multiple providers. A consulting team may need to work across existing contracts and platforms before a client can replace a single component. Its ability to manage those relationships can be as important as the ability to build new features. Synpulse’s company profile
Marsh reported about $27 billion in consolidated revenue for 2025. Its investor presentation put annual revenue for Marsh Management Consulting at $3.6 billion and described more than 7,000 professionals across a grouping that includes Oliver Wyman, NERA Economic Consulting and Lippincott. The presentation gives a sense of the buyer’s wider reach. It leaves open what proportion of Oliver Wyman work involves systems implementation, how much revenue Synpulse contributes and what share of the two firms’ customers overlap. Dividing the management consulting figure by the number of Synpulse staff would mix different businesses and tell an investor little about the purchase. Marsh’s full-year results · Marsh’s investor presentation
Consider the buyer’s May announcement of its proposed acquisition of CR3 Partners. It said 62 professionals would join from a firm specialising in restructuring and turnaround. Bringing a team of roughly 1,200 into the group presents a different problem of scale. Synpulse has delivery teams across several regions and specialises in moving technology changes through regulated institutions. The comparison is useful for seeing what has to be integrated. The financial terms needed for a price comparison remain private. Oliver Wyman’s CR3 announcement
The companies say they have already combined staff on several projects. That prior work supplies a baseline for evaluating what changes under common ownership. Can the teams commit scarce specialists earlier because they share staffing plans? Does a client get a single statement of work for design and implementation? Can a delivery lead change a design when a migration rehearsal exposes a weakness? Under a partnership, two firms can sometimes do these things with good contracts and a strong relationship. The purchase adds value to the extent that it makes such coordination reliable across engagements.
Consultancy.eu reported that Synpulse will keep its brand and leadership, while the parties have yet to set out detailed plans for longer-term integration. Local teams possess client relationships, know how existing systems work and can explain decisions to local risk and operations teams. Those relationships give continuity some value. The buyer still has to make commercial incentives work across the firms. If a strategy practice receives credit when a project is sold and a delivery practice carries the overruns, the new ownership would leave the client facing the familiar problem of two teams with competing incentives. Consultancy.eu’s transaction report
A core banking migration shows what clients are hiring for#
Synpulse’s public work with Australia’s Judo Bank illustrates why an implementation capability has its own value. The firms announced completion of a core banking transformation phase in 2025. A 2026 case discussion with Judo’s delivery enablement lead describes a two-year re-platforming effort. This is a supplier and client account of a specific project, with its own scope and starting systems. It establishes a concrete class of work to look for in Synpulse’s business. A reader would need cost, service and comparison data to use it as a general measure of delivery performance. Judo Bank project announcement · Judo Bank case discussion
A core system maintains records that other services depend on. Moving it can touch account balances, transaction history, posting rules, customer identifiers, reconciliations and downstream reports. Before accepting the new system, a bank needs to confirm that the same business events produce expected results with actual data conditions. Clean examples test the happy path. Exceptions such as a missing historic field or a corrected transaction reveal whether migration and reconciliation rules have captured what the bank already does. Business specialists and engineers need to agree on how to handle those cases.
Time spent proving continuity can dominate even when new features are easy to demonstrate. A launch plan might include a reconciliation deadline, an agreed capacity for manual review and a clear decision point for moving back to the previous system. An experienced delivery team can estimate the work using records of rehearsal sizes and discrepancies. A planning team can use those figures to adjust the budget and scope before launch week. The value of an integrated practice is that delivery evidence can change a board-level decision early enough to matter.
Suppose a rehearsal reconciles 99.9 percent of accounts while leaving a mismatch concentrated in a small group of borrowers whose interest terms changed during a previous system upgrade. The headline percentage offers limited guidance for the launch decision. The remaining cases could be simple to review individually, or they could expose a rule that applies again next month. A business owner needs to determine which, and the engineer needs time to reproduce and confirm the fix. When both teams share a delivery plan, the sponsor can decide whether to narrow the rollout or postpone it with a clear view of the consequences. This example illustrates an acceptance problem that headcount alone cannot solve.
Choices after launch are also part of the purchase decision. An implementation team may identify extra processing introduced by a data conversion, or a mismatch between what a branch agent sees and what appears on a customer statement. The fix may require a developer familiar with a supplier’s product, a bank employee authorised to approve it and an operations manager who can check the reconciliation. Financial institutions pay for the coordination that gets this work done smoothly, even when the improvement users eventually see is a single corrected field.
Synpulse lists specialties including core systems, wealth platforms and regulatory change. It works with partners across the technology a bank has already purchased. A record of successful projects can shorten discovery, because an adviser knows which questions to ask about data ownership and legacy dependencies. It also creates a procurement question. A client needs to know whether any payment relationship affects the selection of a platform and whether it can choose a technology that sits outside the provider’s usual network. Capability and independence are both important when a recommendation turns into a multi-year contract. Synpulse’s banking practice
The financial case depends on selling and staffing the same work#
The purchase can widen the kind of contract Oliver Wyman can bid for. A bank might commission an assessment, then follow with procurement, migration and operational readiness. These often have separate budgets and risk profiles. The people who estimate a project may forecast several years of activity. A delivery agreement is won only when the scope, client controls and commercially acceptable terms are in place. Distinguishing proposals, signed contracts, delivered work and recognised revenue gives investors a clearer view of the value of the combined pipeline.
The other route runs through Synpulse’s installed relationships. A team helping a bank introduce a new payments platform can encounter a question about the economics of expanding a service to another region. Oliver Wyman could have relevant strategic capacity. A common owner can give both teams a reason to bring each other into the account. Success requires incentives that reward successful client outcomes. A client can reasonably prefer one workstream at a time, especially when it wants to keep independent oversight of a project.
Billing models determine who absorbs uncertainty. A fixed-price migration package may give a client budget visibility while leaving the supplier to cover more work if the data differ materially from the specification. Time and materials may limit the consultancy’s exposure, with more variability appearing on the client’s invoice. Additional staff can allow several deliveries to proceed together, provided the right experience is available. A shortage of specialists familiar with a particular system brings deadlines and margins back into contact.
A client can buy the work in stages. It might pay for a short discovery engagement with deliverables it can use in a competitive tender, then commission migration only when scope and obligations are clear. The consultancy can bid confidently because it has seen the system. The customer keeps the option to bring in a different implementer. This arrangement leaves some potential revenue uncommitted from the buyer’s perspective, and it provides a meaningful test of the firms’ combined offer. If the client chooses to retain both teams after seeing the discovery work, the result says something about the price and expertise on offer.
Margins also depend on the time staff spend between engagements, compensation and the mix of work. Keeping a bench of specialists available makes it easier to accept a new contract on short notice. The same capacity absorbs cost while it waits. Moving people across regions may help wider programmes and still require local language, know-how and authorisation. Integrating hiring, training and deployment schedules could improve utilisation. It must preserve the availability of senior people when a project needs someone to make a difficult decision rather than manage work already planned.
The release gives no purchase price, payment structure, target revenue or margin. It provides no revenue target for combined projects and no timetable for cost savings. The announced staff count is an operating input. For a deal of this kind, the first useful financial disclosures could include acquisition spending and an attribution of later revenue growth to purchased versus existing operations. Deal-specific disclosure may be limited, especially within consolidated accounts. Readers should look for the accounting perimeter before interpreting any group figure as proof of return.
AI will meet the budget for operations, testing and control#
Both sides mention AI engineering in the case for the deal. Financial institutions can use it in different places, from helping employees find approved policies to preparing drafts for human review. Those systems have different access and sign-off needs depending on the work they support. A tool that drafts a summary of public policy documents needs a different review from a system that uses account data to shape what a customer is offered. An adviser helps the buyer establish the level of evidence and control each use needs before assigning engineering capacity.
Take a hypothetical internal assistant that suggests which document an operations employee should use to resolve an unusual request. Its output is valuable when it finds the current procedure and sends ambiguity to a qualified person. A bank would need to know which staff can see the result, what evidence the answer cites and whether updates to approved procedures reach the assistant in time. If it fails, the employee needs a usable fallback. An implementation consultancy can bring those questions into tests and acceptance criteria so that a successful demonstration has a path to a working deployment.
Return calculations for such systems depend on the denominator. Reducing average lookup time by a minute is valuable only for the part of the work for which the assistant is eligible. Some requests may still require extra review, and a system can incur ongoing expenses for hosting, identity controls, evaluation and support. A credible budget includes pilot work, integration, exception handling and the costs of running the service later. A reduction in handling time can coexist with an increase in total cost if the pilot reaches too few eligible cases.
Bank staff also need to be able to explain results from the software they use. Project records can connect a policy version to a deployed configuration, a set of observed outputs and a roll-back decision. That documentation lets a bank learn whether a problem came from the input, the model or the protocol for escalation. For an adviser selling broad transformation work, those tasks are part of the implementation commitment. Their cost can become visible after a pilot has already won attention for being fast.
The deal announcement offers no joint AI product price, contracted rollout numbers or outcome data. A buyer can nevertheless look at how the firms perform the ordinary work of delivery. They have to draw a connection between the claimed benefit, the records that verify it, the controls that protect customers and the people who will maintain the system. The principal opportunity here is selling more of that work on a credible basis. AI makes the handover between business decisions and system operations more valuable in the projects where it introduces new dependencies.
One supplier simplifies some decisions and concentrates others#
Financial institutions also have to understand who performs important work when they rely on outside firms. The Basel Committee’s principles on third-party risk describe oversight of providers and arrangements, including continuity and exit planning. Local supervisory regimes determine how specific requirements apply. An engagement in which a provider supplies strategy, design and support can simplify the list of contracts and still increase how much the customer depends on that provider. This is a question about the practical ability to keep operating when an arrangement changes. Basel Committee principles for third-party risk
The customer needs to see the boundaries that matter inside the contract. Can it inspect the records used in delivery? Who owns technical documentation and configurations? Can it employ another firm to maintain a component later and obtain the underlying materials? If a key subcontractor stops working, what happens to its services? A combined consultancy with a large partner network can make access to skills and geographic coverage easier. Those same relationships can call for explicit responsibilities and contingency plans.
The point becomes visible when a support agreement expires. The people authorised to approve a change need a current runbook, access to the relevant records and colleagues who have rehearsed the procedure. A contractual right to receive documentation has limited value if the document reflects a system that was replaced six months earlier. A client paying for a complete delivery can ask for a practical handover test as part of acceptance. The test measures whether a replacement team can understand an incident, identify the responsible component and carry out the next approved step using the records the original team supplies.
Clients may also want an independent review at important points. The people who design an implementation can perform their own checks and explain the results. Separate reviewers can examine whether the testing conditions answer the client’s risk questions. A bank might choose a single party for day-to-day work while keeping acceptance authority and audit access within its own organisation. Deal integration will be more useful to clients if it keeps room for those arrangements, because finance executives still have to answer for the systems their institutions operate.
Employee retention is an immediate operating measure after closing. Around 1,200 employees represents a substantial pool of experience, but the teams and people needed by one customer can be a small part of that pool. A client in the middle of a rollout may need the same migration lead through the first quarter of live operation. The deal release says the staff will continue working from offices on three continents. The useful follow-up is how staffing, client escalation and decision rights work in practice when two teams have current contracts and different reporting lines.
Marsh serves institutions across different activities, and Oliver Wyman and Synpulse work with established clients and software partners. A larger network gives the combined consultancy more potential counterparties. It also raises the importance of disclosure about roles and interests. A client evaluating vendor selection, implementation and long-term support needs confidence that commercial incentives are visible. The public announcements give the rationale for coming together. They leave contract governance to what the parties and clients actually agree.
The milestones that would make the acquisition legible#
For now, the public facts are an agreement, an expected early-2027 closing window and an operating rationale based partly on previous joint project work. The first milestone is the completion notice, including any conditions identified in later disclosures. Next come the appointments and delivery arrangements that show whether the firms can coordinate across regions while lending continuity to Synpulse’s projects. Public evidence of work jointly won or launched after closing would help separate the effect of ownership from collaborations that already took place.
Financial results are a later test. New implementation contracts can contribute revenue and bring more cost in salaries, training and specialist capacity. A deal can widen a firm’s remit while making its delivery commitments more demanding. Evidence of retention combined with the value and performance of delivered engagements would explain more than a one-time increase in reported staff numbers. Marsh’s consolidated disclosures may offer information on the acquisition, but the published material can leave individual client economics private.
The customer can reach a conclusion sooner than the outside investor. A project sponsor will know whether business and engineering leads share a scope, whether the supplier can reconcile records before cutover, whether risk staff see the evidence they need and whether the support team can handle the first weeks after launch. Those are practical tests of whether bringing work under common ownership removes the gaps clients pay to manage. The advantage is strongest when a bank can see who decided, who implemented and who will respond when the system is live.
Oliver Wyman already had a relationship with Synpulse. The proposed acquisition is a decision to put capital and management responsibility behind that relationship. Its size in people makes it worth watching, and its price remains unknown. The outcome will turn on a more visible question than the eventual transaction multiple. Can the combined teams carry changes further into a bank’s operations while giving the client enough visibility and control to trust the work?